24 September 2026
Market Comparison · Western Hyderabad
Kokapet vs Financial District vs Tellapur: Which West Hyderabad Corridor Should You Buy In?
Three corridors, one decision. A buyer's comparison of land title, road access, metro, price bands, rental yield and product type — with the Kokapet and Neopolis figures drawn from HMDA's auction record and Brigade's disclosures, and the other two corridors kept honest.
Contents
If you are searching for the best area to buy a flat in west Hyderabad, you have almost certainly narrowed it to three names: Kokapet, the Financial District and Tellapur. They sit in the same broad western growth belt, they sell to the same pool of technology and finance professionals, and the brochures for all three promise the same things. The differences that matter — who owned the land before the developer, how you get onto the Outer Ring Road, whether a metro exists or is merely proposed, what a square foot costs and what it rents for — are the ones the brochures skip. This guide puts them side by side.
How we compared the corridors
We scored each corridor on six things a buyer can actually check: the land and title story, road access, metro, the prevailing price band, rental yield and the kind of product being built. One rule governs the comparison. For Kokapet and Neopolis we use figures from HMDA's published auction record and Brigade's own project disclosures, which is what we work with every day. For the Financial District and Tellapur we do not quote rates, sizes or possession dates we have not verified against a developer's RERA filing or cost sheet — we tell you what to verify and how. A comparison that invents numbers for two of its three columns is not a comparison; it is a sales pitch.
Kokapet and Neopolis
Neopolis is an HMDA-planned greenfield layout at Kokapet, in Gandipet Mandal of Ranga Reddy district, on the western edge of Hyderabad. It has a dedicated trumpet interchange onto the Outer Ring Road and sits roughly two kilometres from the Financial District.
What makes it unusual in Indian real estate is that the land came to market through HMDA auctions, plot by plot, with clean government-derived title. Almost every parcel has been bought by a listed or national developer. There is no fragmented ownership, no unclear revenue records and no encroachment history. That is rarer than it should be.
The land auction record tells the story better than any market commentary. In the November 2025 round alone, HMDA raised Rs 1,353 crore from 9.06 acres against an upset price of Rs 99 crore an acre, and Plot 15 went at Rs 151.25 crore an acre — the highest per-acre land price in Hyderabad's history. Brigade's Plot 20 acquisition at Rs 118 crore an acre in December 2025 sits below the peak of the same cycle. The full table and the developer roster are on our Neopolis Kokapet page.
Road access. Neopolis has the ORR trumpet interchange, which gives it road access most western Hyderabad micro-markets do not have. Distances below are approximate and measured by road; drive times vary with traffic, so verify at your own commute hour during a site visit.
Metro — read this honestly. There is no operational metro serving Kokapet or Neopolis as of 2026. The proposed extension into this corridor remains in long-term planning and is not funded. This is the micro-market's single genuine infrastructure weakness, and anyone telling you otherwise is selling. What Neopolis has instead is the ORR trumpet interchange, which gives it road access most western Hyderabad micro-markets do not have.
Price band. Prevailing residential rates in 2026: outside Neopolis, roughly Rs 9,000 to Rs 12,000 per sq ft. Premium Neopolis high-rises, Rs 12,000 to Rs 14,000. Ultra-luxury and sky-villa product, Rs 14,000 to Rs 17,500 and above. Brigade Barcelona at approximately Rs 13,870 per sq ft sits at the top of the premium band.
Rental yield. The honest underwriting note: rental yields in the corridor run three to four per cent. This is a capital appreciation market driven by land scarcity and employment proximity, not an income market. And the absence of metro is a real constraint on how far the corridor can broaden its buyer base.
Product type and social infrastructure. Large-format high-rise apartments from listed and national developers — the developer set inside Neopolis and Kokapet includes Godrej Properties, Rajapushpa, My Home, Prestige, Sattva, Phoenix, Sumadhura, Candeur, Poulomi, Lansum, DSR and SSI. Social infrastructure is shared with the Gachibowli and Nanakramguda belt: Continental Hospitals, AIG Hospitals and Care Hospitals for healthcare; Indus International, Oakridge International, CHIREC International, Rockwell International and Birla Open Minds among the schools serving the location, with Phoenix Greens and Glendale Academy also serving the western corridor; Marriott, Sheraton and Hyatt for hospitality; and Sarath City Capital Mall and Inorbit Mall at Madhapur for retail.
Financial District
The Financial District is the employment core that Kokapet sells proximity to — the office campuses whose commute every Neopolis brochure quotes in minutes. Buying inside the corridor rather than two kilometres outside it is a legitimate choice, and a different one.
What we can say from our own working numbers is limited to geography: the Financial District is approximately two kilometres from Neopolis, Nanakramguda is the adjacent employment node roughly four kilometres from Plot 20, GAR Infobahn is an office campus roughly three kilometres away, and Continental, AIG and Care hospitals at Gachibowli and Nanakramguda serve both corridors. Everything else about buying here you should verify project by project, and we would rather say so than quote a figure we have not checked.
What to verify. Land title first. Unlike Neopolis, the residential land in and around the Financial District did not come to market through a single government auction programme, so the title chain is specific to each project — ask for the link documents and the encumbrance certificate, not a summary. Road access: which ORR interchange the project actually uses, and how its internal roads behave at peak hour. Metro: confirm the current status of any line the brochure mentions; a proposed alignment is not a station. Price band: get the rate per sq ft on super built-up area and on RERA carpet area separately, from the developer's current cost sheet, and compare like with like. Rental yield: ask for actual signed leases in the same tower or a delivered neighbour, not projections. Product type: verify whether the tower you are considering is residential-only or part of a mixed-use block, which changes maintenance, parking and resale.
Tellapur
Tellapur tends to enter a shortlist as the value alternative. The pitch is more built-up area for the same cheque, at the cost of a longer commute to the Financial District and Gachibowli. Treat that as a hypothesis to test on the cost sheet, not as a fact — we have not verified Tellapur rates, sizes or possession dates and will not quote them here.
What to verify. Land and title: the ownership history of each parcel — who assembled it, whether any portion carries pending litigation or land-use conversion issues, and whether the layout approval covers the whole site rather than a first phase. Road access: the actual route to the Outer Ring Road and to Gachibowli at nine in the morning, driven by you, not estimated from a map. Metro: as with the other two corridors, confirm the present status of any proposed line before you price it in. Price band and yield: the per-sq-ft rate on super built-up and on RERA carpet area from the developer's current cost sheet, and signed rental agreements in delivered towers nearby. Product type: check the tower count, density per acre and the phasing plan for whichever community you shortlist, because a project delivered in phases lives with construction for years.
Comparison table
| Corridor | Land and title story | Road access | Metro | Price band, 2026 | Rental yield | Best for |
|---|---|---|---|---|---|---|
| Kokapet and Neopolis | HMDA auctions, plot by plot, clean government-derived title; almost every parcel held by a listed or national developer | Dedicated ORR trumpet interchange; approx 2 km to the Financial District | None operational as of 2026; extension in long-term planning, unfunded | Premium Neopolis high-rises Rs 12,000 to Rs 14,000 per sq ft; ultra-luxury Rs 14,000 to Rs 17,500 and above; outside Neopolis Rs 9,000 to Rs 12,000 | Three to four per cent | Capital appreciation buyers; end users working in the Financial District, Nanakramguda or Gachibowli |
| Financial District | Project-specific — verify link documents and the encumbrance certificate | Verify the interchange used and peak-hour internal roads | Verify current status; do not price in a proposed line | Verify on the developer's cost sheet, on SBA and RERA carpet separately | Verify with signed leases | Buyers who want to live inside the employment core and accept mixed-use surroundings |
| Tellapur | Project-specific — verify ownership history and full layout approval | Verify the drive to the ORR and Gachibowli at your commute hour | Verify current status; do not price in a proposed line | Verify on the developer's cost sheet | Verify with signed leases in delivered towers | Buyers prioritising built-up area per rupee over commute time |
Which buyer fits which corridor
The capital-appreciation buyer. Kokapet and Neopolis, on the numbers we hold. Land scarcity is documented in HMDA's own auction record, the title is auction-clean, and the employment proximity is two kilometres by road. Go in knowing the yield is three to four per cent and that there is no metro.
The end user working in the Financial District, Nanakramguda or Gachibowli. Kokapet or the Financial District itself. The choice is whether you want to live inside the employment core — with everything a mixed-use environment brings — or two kilometres outside it in a planned residential layout with lake frontage. Drive both at your own hour before deciding.
The area-first buyer. Tellapur is where that search usually leads, and it may well be right — but only once the per-sq-ft rate on RERA carpet area, the title chain and the commute have been verified rather than assumed.
The income-first buyer. Be careful in all three. On the figures we hold, Kokapet is not an income market at three to four per cent; for the other two corridors, ask for signed leases before you believe a yield.
The NRI buyer. NRIs and PIOs may purchase residential property in India under the general permission granted by the Reserve Bank of India, with payment routed through NRE, NRO or normal banking channels. Clean government-derived title is worth more to a buyer who cannot attend the sub-registrar's office in person, which is one reason Neopolis draws overseas enquiries; we handle documentation and power of attorney for overseas buyers.
Brigade Barcelona in this frame
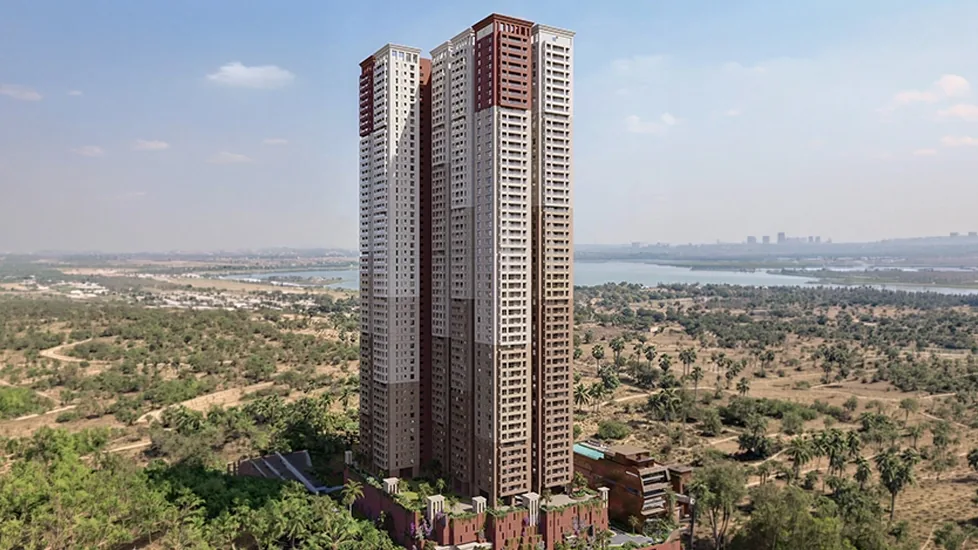
Brigade Barcelona is the project that made us write this guide, so here is where it sits. It is a single tower on 4.05 acres at Neopolis Phase 3, Plot 20, carrying 666 residences of three and four bedrooms with study-plan variants, oriented to the lake, with architecture by Ricardo E. Bofill. Super built-up areas run from 2,790 to 3,764 sq ft and RERA carpet areas from 1,873 to 2,520 sq ft. Official pricing opens at Rs 3.87 crore, roughly Rs 13,870 per sq ft on super built-up area — the top of the premium band, below ultra-luxury.
On the corridor tests above: the land is auction-clean, bought outright at an HMDA e-auction in December 2025 at approximately Rs 118 crore an acre, roughly eighteen per cent of the project's stated revenue potential of over Rs 2,700 crore. Road access is the Neopolis trumpet interchange, two kilometres from the Financial District. There is no metro, and we say so. The project is registered with Telangana RERA under P02400011156, with HMDA plan approval 2348/HMDA/SWBP/2026 dated 27 July 2026 and a RERA-filed possession date of 27 July 2031. The clubhouse runs across five levels, an eco-deck carries the landscape above the parking, and a rooftop skywalk with dedicated wellness zones tops the tower.
Two honesty notes carry over from the rest of this site. Brigade has published eight amenities plus the launch-announcement features; wider amenity lists on portals are not developer-confirmed. And Brigade has not yet published a specification annexure — the binding document is the annexure attached to your agreement of sale. See the price list, floor plans and location page for the detail.
Frequently asked questions
Which is the best area to buy a flat in west Hyderabad?▾
How far is Kokapet from the Financial District, Gachibowli and HITEC City?▾
Is there metro connectivity in Kokapet?▾
What are residential rates in Kokapet in 2026?▾
What rental yield does Kokapet offer?▾
What makes Neopolis land different from the rest of west Hyderabad?▾
Shortlisting corridors? Start with the numbers.
Get the Brigade Barcelona cost sheet and current floor and facing availability, then compare it line by line against any Financial District or Tellapur cost sheet you are holding. Site visits seven days a week.
Book a Site Visit